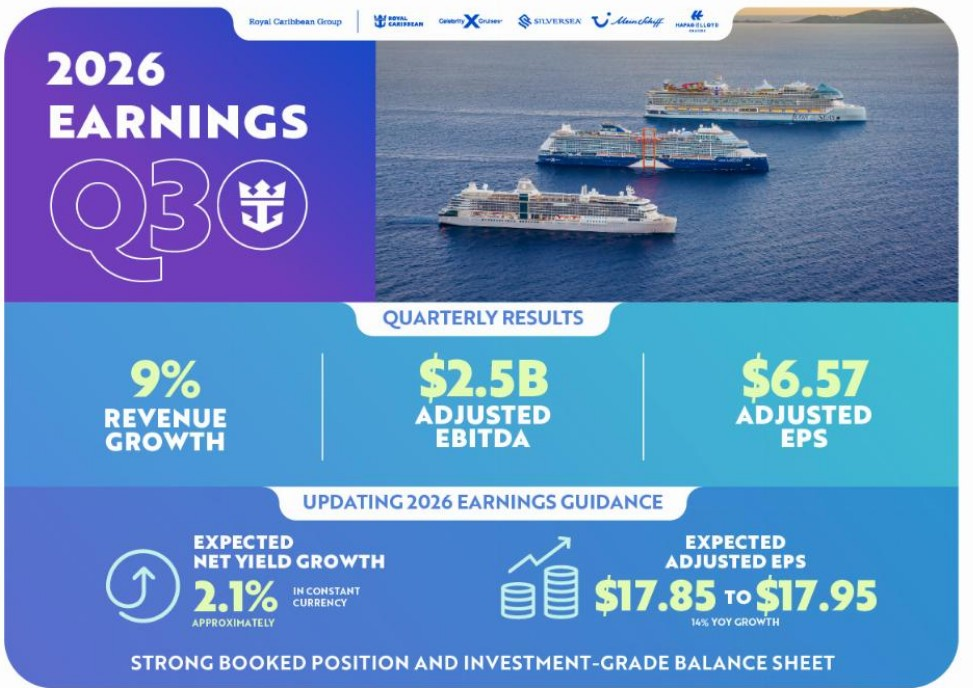
MIAMI, Florida – 27 October 2026 – Royal Caribbean Group reported third-quarter 2026 revenue of $5.6 billion, up 9% year on year, and raised its full-year adjusted earnings guidance after strong close-in demand and expenses shifting into the fourth quarter helped results exceed expectations.
Net income reached $1.7 billion, or $6.45 per share, compared with $1.6 billion and $5.74 per share in the same period last year. Adjusted net income was $1.8 billion, while adjusted EPS was $6.57 and adjusted EBITDA reached $2.5 billion.
The company now expects full-year adjusted EPS of $17.85 to $17.95. The higher outlook reflects stronger-than-expected third-quarter performance, partly offset by higher-than-anticipated fuel costs, based on current at-the-pump prices, and currency exchange rates.
Close-in demand supports third-quarter yields
Third-quarter capacity increased 8% year on year, while Royal Caribbean Group carried 2.7 million guests, up 9%. Load factor was 112%. Gross margin yields declined 0.8% as reported, while net yields increased 0.9% as reported and 0.6% in constant currency. Net yield growth exceeded guidance, primarily due to better-than-expected close-in demand in Europe and the Caribbean.
Gross cruise costs per available passenger cruise day (APCD) decreased 0.7% as reported. Net cruise costs excluding fuel per APCD declined 1.9% as reported and 1.8% in constant currency, with better-than-expected cost performance resulting from expenses shifting into the fourth quarter.
Jason Liberty, Chairman and CEO of Royal Caribbean Group, said: “Our third quarter results reflect continued strong consumer demand for our vacation experiences and the accelerated momentum across our industry leading brands.”
He said the Group’s strategy is using its brands, differentiated experiences, loyalty platform and technology capabilities to deepen guest relationships, increase vacation frequency and capture a greater share of the global vacation market.
2027 bookings pace ahead of historical levels
Since the previous earnings call, booking volumes have increased in the mid-teens across major channels, while bookings for 2027 sailings are up in the high teens.
Royal Caribbean Group said that, while it was still early, 2027 bookings were pacing ahead of historical levels at higher rates.
Third-quarter pre-cruise and onboard revenue rates were ahead of the prior year, while fourth-quarter pre-cruise revenue rates are also booked ahead of last year. Based on the forward fuel curve, Royal Caribbean Group said it remains on track to achieve its Perfecta goals. These include 20% compound annual growth in adjusted EPS from 2024 through 2027 and return on invested capital of at least 17% by the end of 2027. The company said it was already above its ROIC target.
Sandals investment expected to close in early 2027
The results update also addressed Royal Caribbean Group’s agreement to acquire a 50% interest in Sandals and Beaches Resorts. The portfolio includes 18 resorts across the Caribbean, three resorts under development and more than 1,000 acres of undeveloped Caribbean land.
Approximately 30% of Royal Caribbean Group guests also take all-inclusive holidays, while a similar proportion of Sandals and Beaches guests also cruise.
The transaction is expected to close in early 2027, subject to customary closing conditions and regulatory approvals. Royal Caribbean Group expects its share of earnings from Sandals and Beaches Resorts to be immediately accretive, with the 2027 contribution dependent on the timing of completion. The investment is expected to be accounted for under the equity method, with results reported on a one-quarter lag. Its expected contribution will be incorporated into Royal Caribbean Group’s 2027 guidance upon closing.
Full-year revenue forecast to rise 9%
Royal Caribbean Group expects full-year 2026 revenue to increase 9% year on year. Net yields are forecast to rise approximately 2.7% as reported and approximately 2.1% in constant currency. Net cruise costs excluding fuel per APCD are expected to increase approximately 0.4% as reported and remain approximately flat in constant currency.
Fourth-quarter adjusted EPS is expected to range between $3.48 and $3.58, while revenue is forecast to increase 9% year on year.
At 30 September 2026, the company reported liquidity of $7.4 billion, including cash, cash equivalents and undrawn revolving credit capacity.
Full-year capital expenditure is expected to total approximately $4.6 billion, primarily relating to the company’s new ship order book and land-based destination initiatives.
Source: Official Press Releases from Royal Caribbean Press Centre, 27 October 2026, Miami